Business Loan Rejection Reasons: Common Mistakes That Reduce Your Approval Chances
Applying for a business loan can help you expand your business, manage working capital, purchase equipment, or meet urgent financial needs. However, a business loan application may be rejected if the lender finds concerns with your credit history, financial records, cash flow, or repayment capacity.
Understanding the common business loan rejection reasons can help you identify potential problems before applying. By preparing your documents and reviewing your financial position, you may improve your chances of finding a suitable business loan.
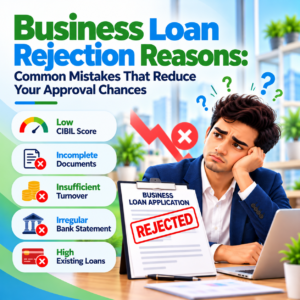
Business loan rejection reasons and common application mistakes
Common Business Loan Rejection Reasons
1.Low CIBIL Score or Poor Credit History
Your CIBIL score and credit history can influence a lender’s assessment of your application. Missed EMI payments, overdue accounts, or a high level of outstanding debt may raise concerns about repayment behaviour.
Tip: Review your credit report, correct any errors, and pay existing loan EMIs on time.
2.Insufficient Business Turnover or Cash Flow
Lenders assess whether your business generates enough income to manage the proposed loan repayments. Low turnover, irregular income, or limited cash flow may affect your business loan eligibility.
Tip: Maintain accurate financial records and ensure that business transactions are properly documented.
3.Incomplete or Incorrect Documents
Missing bank statements, inconsistent income tax returns, incorrect business details, or incomplete registration documents can delay the application or lead to rejection.
Tip: Prepare your PAN, identity proof, business registration details, bank statements, income tax returns, and applicable GST records before applying.
4.High Existing Loan Obligations
If your business already has several loans or substantial monthly EMI commitments, the lender may question whether you can comfortably manage another repayment.
Tip: Review your current liabilities and calculate your repayment capacity before requesting additional funding.
5.Irregular Bank Statements
Frequent cheque bounces, repeated negative balances, unexplained transactions, and inconsistent income credits may raise questions during loan assessment.
Tip: Keep business and personal transactions separate wherever possible and maintain clear, consistent banking records.
Other Factors That May Affect Business Loan Approval
Other reasons for business loan rejection can include a short business operating history, inconsistent financial statements, insufficient repayment capacity, or a business profile that does not meet the lender’s requirements.
Eligibility criteria vary across banks and NBFCs. A rejection from one lender does not necessarily mean that every lender will reject your application.
How to Improve Your Business Loan Approval Chances
Before applying for a business loan, consider these practical steps:
Improve your credit profile: Pay existing EMIs on time and address overdue accounts.
Maintain healthy cash flow: Track business income, expenses, and upcoming payments.
Organize financial documents: Ensure your bank statements and tax records are accurate and up to date.
Choose a suitable loan amount: Request funding based on your business requirements and repayment capacity.
Compare loan options: Review eligibility criteria, interest rates, fees, and repayment terms before choosing a lender.
Business loan eligibility, bank statement analysis and approval tips
How BorrowRight Can Help
BorrowRight provides loan advisory support for businesses exploring suitable business loan, MSME loan, and working capital financing options. Understanding your financial profile and funding requirements can help you explore options that may fit your needs.
Before applying, review your eligibility, prepare the required documents, and understand the repayment commitments associated with the loan.
Conclusion
Understanding business loan rejection reasons can help you avoid common application mistakes. Credit history, business turnover, bank statements, existing liabilities, and incomplete documents may all influence a lender’s decision.
Prepare your financial records carefully, assess your repayment capacity, and compare suitable loan options before applying. Although approval cannot be guaranteed, better preparation can help you make a more informed financing decision.
India’s one of the unbiased loan advisor for best deals in loans and unmatched advisory services. We are one stop shop for all types of lending solutions.
 By